
MRP: ₹4541
₹3592
₹ 949 Off
(Incl. of all taxes)
Qty
Buying in bulk?
In stock
Deliver to
- 7-day returns
- Secure payment
- International shipping
- Carefully packed
Get this at ₹ 3412Extra 5% OffAdd items worth ₹999 to the cart & get extra 5% off
Get this at ₹ 3233Extra 10% OffAdd items worth ₹1499 to the cart & get extra 10% off
Book Summary
From the late 1990s, the spectacular growth of a secondary market for credit
through derivatives has been matched by the emergence of mathematical modelling
analysing the credit risk embedded in these contracts. This book aims to provide
a broad and deep overview of this modelling, covering statistical analysis and
techniques, modelling of default of both single and multiple entities,
counterparty risk, Gaussian and non-Gaussian modelling, and securitisation. Both
reduced-form and firm-value models for the default of single entities are
considered in detail, with extensive discussion of both their theoretical
underpinnings and practical usage in pricing and risk. For multiple entity
modelling, the now notorious Gaussian copula is discussed
- ISBN-13
- 9780199669486
- Language
- English
- Binding
- Hard Bound
- Publisher
- Oxford University Press, USA
- Publishing Date
- 2013-01-17
- Total Pages
- 704
The Oxford Handbook of Credit Derivatives (Oxford Handbooks in Finance)
by Alexander Lipton, Andrew Rennie (Author),
Oxford University Press, USA (Publisher)
fictionfantasyyoung adultaward winning
Frequently bought together
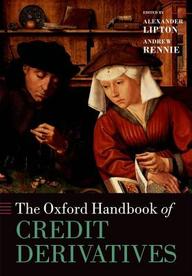 The Oxford Handbook of Credit Derivatives (Oxford Handbooks in Finance)₹3592This item
 Maarikaadu₹63
 Natyamayuri₹63
Total for 3 items₹3718₹4681You save ₹963
Product Specifications
Book Summary
From the late 1990s, the spectacular growth of a secondary market for credit
through derivatives has been matched by the emergence of mathematical modelling
analysing the credit risk embedded in these contracts. This book aims to provide
a broad and deep overview of this modelling, covering statistical analysis and
techniques, modelling of default of both single and multiple entities,
counterparty risk, Gaussian and non-Gaussian modelling, and securitisation. Both
reduced-form and firm-value models for the default of single entities are
considered in detail, with extensive discussion of both their theoretical
underpinnings and practical usage in pricing and risk. For multiple entity
modelling, the now notorious Gaussian copula is discussed
Book Specifications
- ISBN-13
- 9780199669486
- Language
- English
- Binding
- Hard Bound
- Publisher
- Oxford University Press, USA
- Publishing Date
- 2013-01-17
- Total Pages
- 704