
MRP: ₹10665
₹8839
₹ 1826 Off
(Incl. of all taxes)
Qty
Buying in bulk?
In stock
Deliver to
- 7-day returns
- Secure payment
- International shipping
- Carefully packed
Get this at ₹ 8397Extra 5% OffAdd items worth ₹999 to the cart & get extra 5% off
Get this at ₹ 7955Extra 10% OffAdd items worth ₹1499 to the cart & get extra 10% off
Book Summary
This volume is the result of an Advances in Econometrics conference held in
November of 2002 at Louisiana State University in recognition of Halbert White's
pioneering work published in Econometrica in 1980 and 1982 on robust
variance-covariance estimation and quasi-maximum likelihood estimation. It
contains 11 papers on a range of related topics including the estimation of
possibly misspecified error component and fixed effects panel models, estimation
and inference in possibly misspecified quantile regression models, quasi-maximum
likelihood estimation of linear regression models with bounded and symmetric
errors and quasi-maximum likelihood estimation of models with parameter
dependencies between the mean vector and error variance-covariance matrix. Other
topics include GMM, HAC, Heckit,
- ISBN-13
- 9780762310753
- Language
- English
- Binding
- Hard Bound
- Publisher
- Emerald Group Publishing Limited
- Publishing Date
- 2003-12-01
- Total Pages
- 264
Maximum Likelihood Estimation Of Misspecified Models: Twenty Years Later, Volume 17 (Advances In Econometrics)
Frequently bought together
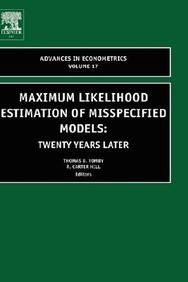 Maximum Likelihood Estimation Of Misspecified Models: Twenty Years Later, Volume 17 (Advances In Econometrics)₹8839This item
 Maarikaadu₹63
 Natyamayuri₹63
Total for 3 items₹8965₹10805You save ₹1840
Product Specifications
Book Summary
This volume is the result of an Advances in Econometrics conference held in
November of 2002 at Louisiana State University in recognition of Halbert White's
pioneering work published in Econometrica in 1980 and 1982 on robust
variance-covariance estimation and quasi-maximum likelihood estimation. It
contains 11 papers on a range of related topics including the estimation of
possibly misspecified error component and fixed effects panel models, estimation
and inference in possibly misspecified quantile regression models, quasi-maximum
likelihood estimation of linear regression models with bounded and symmetric
errors and quasi-maximum likelihood estimation of models with parameter
dependencies between the mean vector and error variance-covariance matrix. Other
topics include GMM, HAC, Heckit,
Book Specifications
- ISBN-13
- 9780762310753
- Language
- English
- Binding
- Hard Bound
- Publisher
- Emerald Group Publishing Limited
- Publishing Date
- 2003-12-01
- Total Pages
- 264