
MRP: ₹12538
₹8904
₹ 3634 Off
(Incl. of all taxes)
Qty
Buying in bulk?
In stock Only 2 left
Deliver to
- 7-day returns
- Secure payment
- International shipping
- Carefully packed
Get this at ₹ 8459Extra 5% OffAdd items worth ₹999 to the cart & get extra 5% off
Get this at ₹ 8014Extra 10% OffAdd items worth ₹1499 to the cart & get extra 10% off
Book Summary
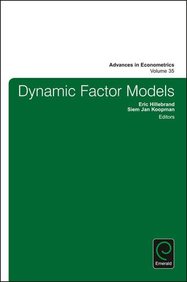
Dynamic factor models (DFM) constitute an active and growing area of research,
both in econometrics, in macroeconomics, and in finance. Many applications lie
at the center of policy questions raised by the recent financial crises, such as
the connections between yields on government debt, credit risk, inflation, and
economic growth. This volume collects a key selection of up-to-date
contributions that cover a wide range of issues in the context of dynamic factor
modeling, such as specification, estimation, and application of DFMs. Examples
include further developments in DFM for mixed-frequency data settings,
extensions to time-varying parameters and structural breaks, for multi-level
factors associated with subsets of variables, in factor
- ISBN-13
- 9781785603532
- Language
- English
- Binding
- Hard Bound
- Publisher
- Emerald Group Publishing
- Publishing Date
- 2016-01-08
- Total Pages
- 410
Dynamic Factor Models (Advances in Econometrics)
Frequently bought together
Total for 3 items₹9030₹12678You save ₹3648
Product Specifications
Book Summary
Dynamic factor models (DFM) constitute an active and growing area of research,
both in econometrics, in macroeconomics, and in finance. Many applications lie
at the center of policy questions raised by the recent financial crises, such as
the connections between yields on government debt, credit risk, inflation, and
economic growth. This volume collects a key selection of up-to-date
contributions that cover a wide range of issues in the context of dynamic factor
modeling, such as specification, estimation, and application of DFMs. Examples
include further developments in DFM for mixed-frequency data settings,
extensions to time-varying parameters and structural breaks, for multi-level
factors associated with subsets of variables, in factor
Book Specifications
- ISBN-13
- 9781785603532
- Language
- English
- Binding
- Hard Bound
- Publisher
- Emerald Group Publishing
- Publishing Date
- 2016-01-08
- Total Pages
- 410